Your smarterclaims pack.
Everything you need to push back on your refused claim: written in your words, in the professional language insurers respect, with the law cited and a clear plan for what to do next.
There's a real argument here, and it's worth making.
Northbridge Travel refused your cancellation claim saying you didn't tell them about a “pre-existing condition”. But under consumer insurance law, an insurer can only turn a claim down for this if you failed to take reasonable care answering their questions. Even then, the remedy usually has to be proportionate, not a flat refusal.
From what you've told us, you answered their medical questions honestly based on what you knew at the time. That puts the burden back on them to show otherwise.
Honest note: we can't promise the insurer will say yes. What we can do is make your argument properly, cite the rules that apply, and set you up to escalate for free if they dig in. That's claiming smarter.
Ready to send.
Copy this into an email or print it. Send it to the insurer's complaints address (we've noted where to find it in your plan). Everything highlighted links to the rule it relies on.
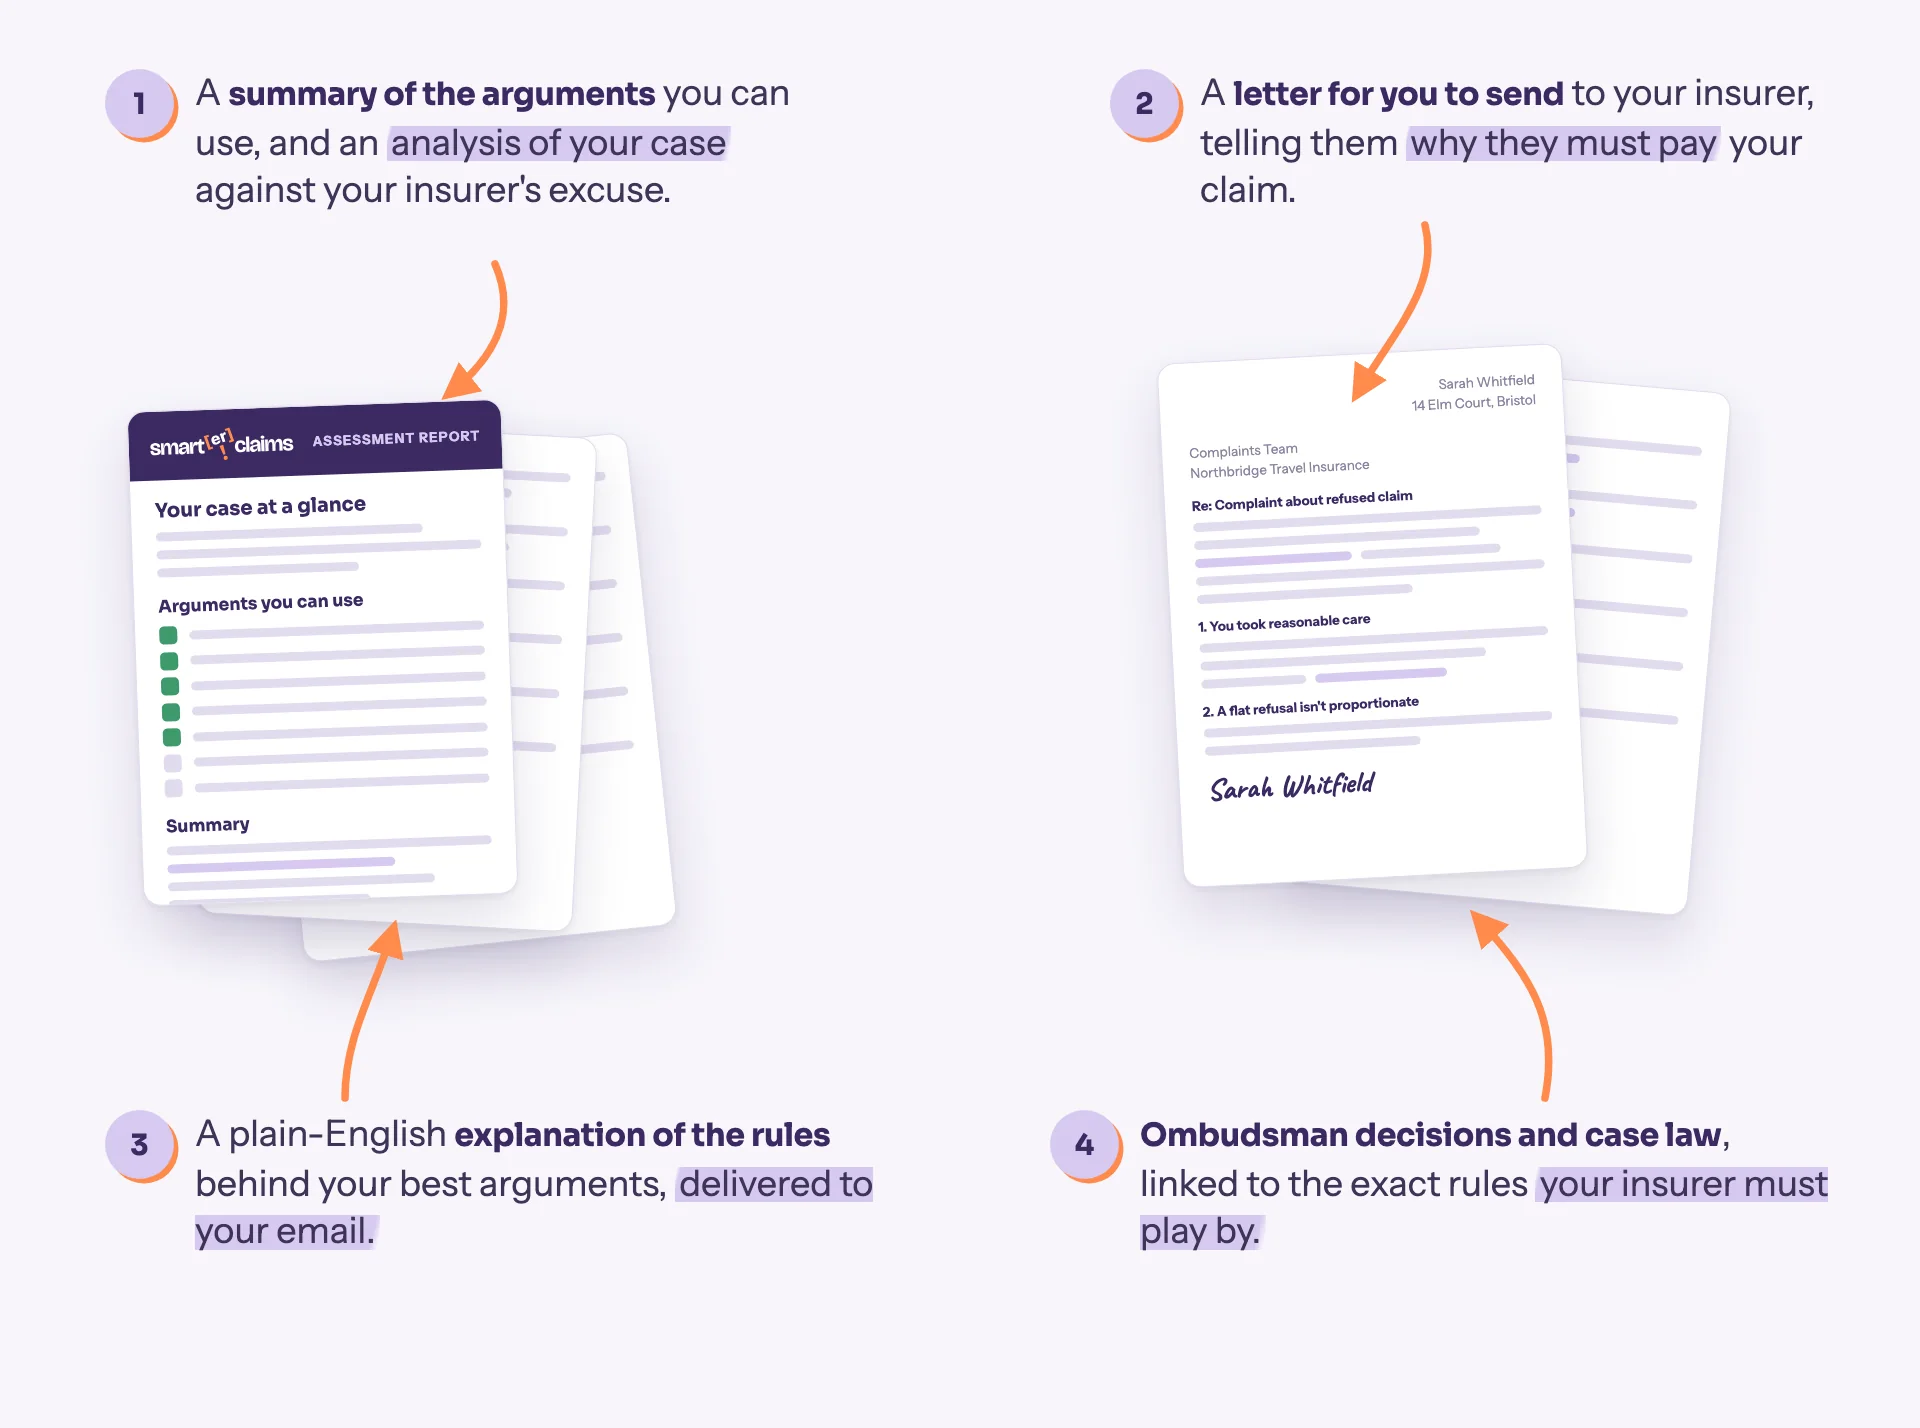
Copy & paste: adjust the bracketed details
Sarah Whitfield
14 Elm Court, Bristol BS1 4XY
sarah.whitfield@example.com
Complaints Team
Northbridge Travel Insurance
[insurer complaints address]
Re: Complaint about refused claim — policy [POLICY NO.], claim ref [CLAIM REF]
Dear Northbridge Travel,
I'm writing to formally complain about your decision to decline my travel cancellation claim, and to ask you to reconsider it.
You declined the claim on the basis that I did not disclose a pre-existing medical condition. I do not accept that decision. When I took out the policy I answered every medical question you asked honestly and to the best of my knowledge at the time. I took reasonable care not to misrepresent my health, which is the standard the law sets for consumers under the Consumer Insurance (Disclosure and Representations) Act 2012.
Under that Act, an insurer can only refuse a claim outright where a consumer made a deliberate or reckless qualifying misrepresentation. If a misrepresentation was merely careless, the remedy must be proportionate — for example, settling the claim in the proportion the premium you paid bears to the premium you would have been charged. A flat refusal is not a proportionate remedy, and you have not shown that any misrepresentation was deliberate or reckless.
I would also remind you of your obligation under ICOBS 8.1 to handle claims promptly and fairly and not to decline a claim unreasonably.
Please therefore reconsider and settle my claim in full. If you maintain your decision, please treat this as a formal complaint and issue your final response so that I can refer the matter to the Financial Ombudsman Service, which I am prepared to do.
I look forward to your reply within 14 days.
Yours faithfully,
Sarah Whitfield
What's going on, and why you have a case.
We explain the real reason behind the refusal and the legal basis for each argument we make. Think of it as a translation of what the insurer is actually saying, so you know exactly what you're dealing with. It's all based on your refusal letter, your policy, and Steve's playbook.
“You didn't disclose a pre-existing condition.”
This is one of the most common reasons travel claims get refused. It only sticks if you genuinely failed to answer their medical questions with reasonable care, not just because a condition existed.
The law expects “reasonable care”, not perfection.
Since 2012, consumers only have to take reasonable care not to misrepresent. If you answered honestly based on what you knew, the insurer can't simply walk away. And if anything was an innocent slip, they usually have to pay a proportionate amount rather than nothing.
They have to prove it. You don't.
It's for the insurer to show a qualifying misrepresentation and that it was deliberate or reckless. Your letter puts that burden back on them and asks them to justify a flat refusal against the proportionate-remedy rule.
This is a strong argument, not a guarantee.
Most refusals like this are worth challenging, and many get overturned at the first letter or at the Ombudsman. But the outcome is theirs to decide. Our job is to give you the best, properly argued shot, and a clear route if they don't budge.
What to do, in order.
Send the letter
Email it to the insurer's complaints team (find the address on your policy documents or their website, under “complaints”). Keep a copy and note the date you sent it.
Give them time to respond
Insurers should acknowledge a complaint promptly and send a final response. If they reconsider and pay, you're done.
If they still say no, go to the Ombudsman
The Financial Ombudsman Service is free and built for consumers. Send them your complaint, the insurer's final response, and this letter. They'll review it independently. We'll remind you exactly how.
Keep everything together
Save your policy, the refusal letter, your sent letter and any replies in one folder. If it goes to the Ombudsman, having it all to hand makes it quick.
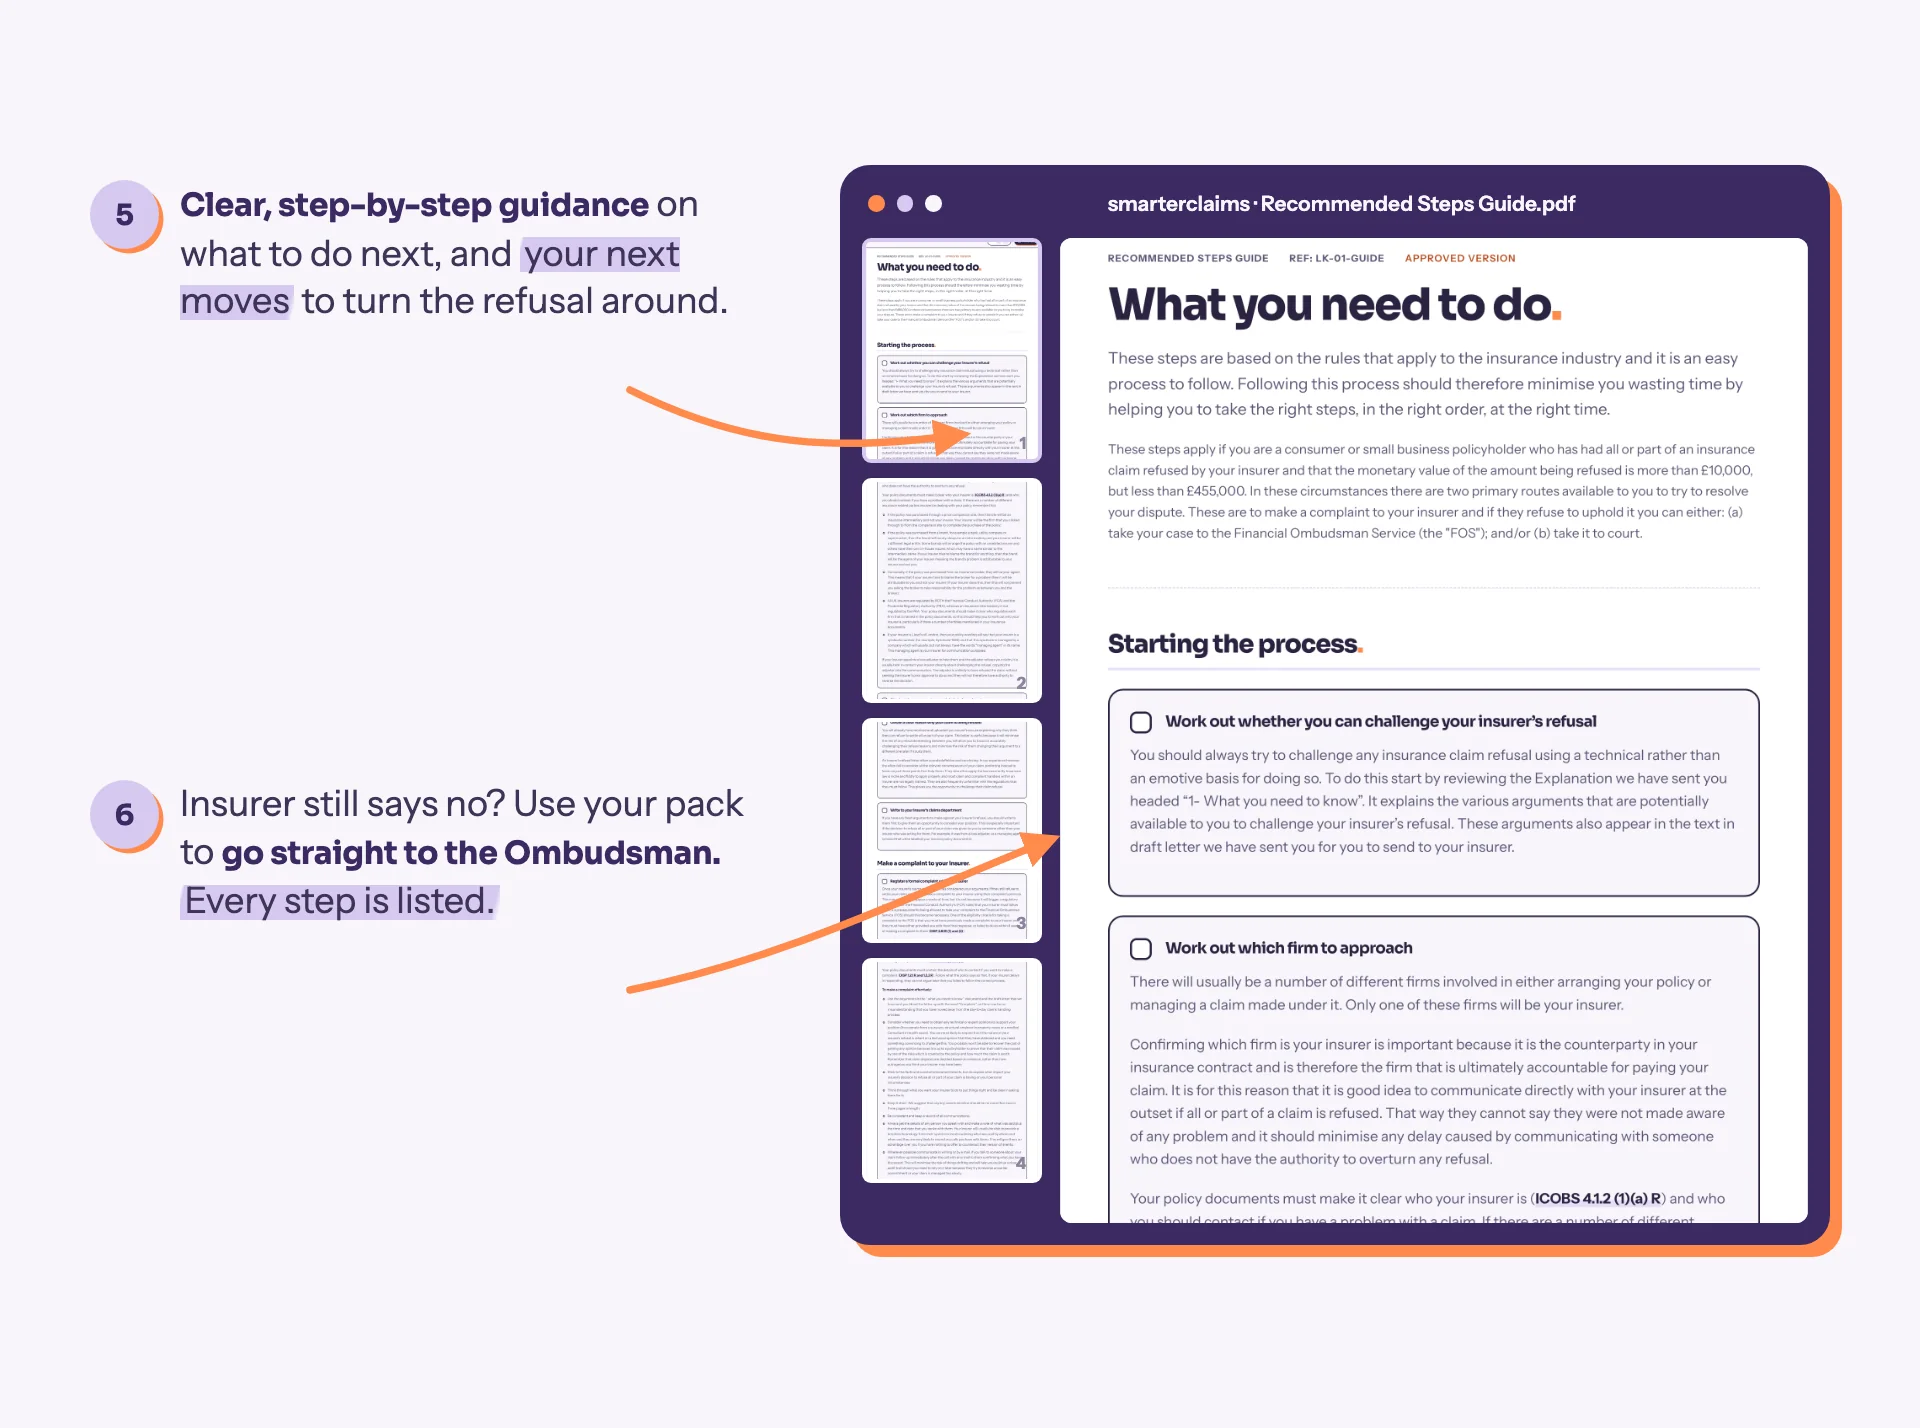
Your detailed action plan
You'll get a detailed action plan and a Smart Guide on how to deal with your insurer, step by step. You get it both as a PDF and as a link.
No-questions-asked money-back guarantee
If this pack isn't useful to you, tell us and we'll refund you in full, no questions asked. You risk nothing by trying.
The case, names, insurer and details above are invented to show what a smarterclaims pack looks like. Your real pack is built from your own letter and policy.
smarterclaims publishes legal information and writes letters you can send yourself, like a digital version of a published legal guide. We're not a law firm and we don't give advice. If your case needs a solicitor, we'll tell you. References to legislation and the Financial Ombudsman Service are for general information.