The offer will not replace your car.

Car insurance write-off valuation too low?

The first offer is rarely their best.

Market value means what it would cost to buy the same car again — not what a trade guide prints. Insurers expect the first number to be accepted. It usually is. It usually should not be.

  • Free to check
  • No account
  • Takes 60 seconds
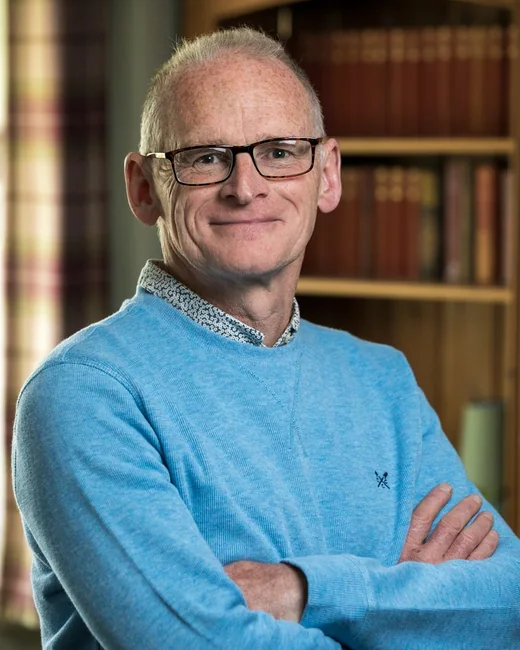
Steve SmartWho's behind thisSteve Smart · Former UK General Counsel, AIGHelped people recover £25M+ from rejected claims

Re: Your claim

Dear ,

We have now completed our review of your claim.

We have valued your vehicle at £4,150 based on industry trade guides. This represents the market value at the date of loss.Your vehicle has been deemed a total loss. Our offer is final and reflects the pre-accident value.The valuation has been calculated using recognised motor trade guides and is not negotiable.

We therefore regret that we are unable to meet your claim on this occasion.

Yours sincerely,

Claims Department

The wording varies between insurers. The argument does not. Typical wording — not a quote from any named insurer.

What they mean

Market-value offers, translated.

When repair costs approach what the car is worth, the insurer writes it off and pays you its market value instead — broadly, what it would have cost to buy the same car, in the same condition, with the same mileage, just before the accident.

To reach the figure they use motor trade guides. That is a reasonable starting point, and it is where the process usually stops.

Where it overreaches

And here is the problem.

A guide figure is not the same thing as what your car actually costs to replace. Guides disagree with each other, sometimes by a lot, and a valuation drawn from whichever one happened to be lowest is not a market value — it is a selection.

The Ombudsman expects better than a single guide. Its approach is to look across the recognised guides rather than accept one in isolation, and it is not sympathetic to insurers landing at the bottom of the range without a reason.

Then there is your actual car, which the guide has never seen: the mileage, the condition, the service history, the recent tyres or cambelt, the specification. And the word "final" in a first offer is a negotiating position, not a fact.

The counter-arguments

How it gets answered.

These are the points that put the burden back where it belongs. Not every one will apply to your case — the letter we write picks the ones that do.

01

Market value means the cost of replacing it — not a printout.

Reframe the conversation, because this is what the phrase actually means. The test is what it would cost you to buy the same car again, and the best evidence of that is what the same car is currently advertised for.

Gather advertisements for genuinely comparable vehicles: same model, similar age, similar mileage, similar condition, and locally where you can. That evidence speaks directly to the question the valuation is supposed to answer.

02

One guide is not a valuation.

Ask which guides they used and what each one returned. The Ombudsman looks across the recognised trade guides rather than relying on one — and where the guides differ and the offer looks unfair, its usual approach is to take the highest of them, unless there is real evidence to justify less.

If they used one guide, or will not say, that is worth raising on its own.

03

Tell them about the car they never saw.

Guides describe an average example. Yours is specific: below-average mileage, full service history, a recent cambelt or new tyres, a higher specification, genuinely good condition.

Set the differences out with evidence — invoices, the service book, photographs, the MOT record. Each is a reason the average is the wrong number for your car.

04

"Final" is not a legal term.

A first offer is an opening position, and insurers know most people accept it. Declining it politely and in writing, with your evidence attached, is a normal part of the process and it very often moves the number.

If it does not, this is exactly the kind of dispute the Ombudsman handles routinely, and it costs you nothing to take it there.

How it works

Four steps.

You do not have to make these arguments yourself. That is what we are for.

Start free now • No documents neededStart free now

Tell us about your problem

Describe in plain English what happened and your current concern. Takes 60 seconds. We'll give you clear guidance on whether we can help and what to do next - completely free. You can start right now, even if you don't have your refusal letter with you.

Upload your documents

Drop your refusal letter and insurance policy. Takes 2 minutes. No account needed.

We analyze & draft

Our system identifies the legal flaws in the refusal and writes a professional rebuttal with citations.

Send & get paid

Send the letter to your insurer. Most reverse their decision. If not, escalate to the Ombudsman.

Start free. Pay only if we can help you win.

  • Step 1 - Free:describe your situation in plain English. Takes 60 seconds. We'll tell you honestly whether we can help and explain next steps.
  • Step 2 - Still free:if we think your case is suitable, upload your refusal letter and policy. We'll do a preliminary review at no charge.
  • Step 3 - Pay only if suitable: once we confirm your refusal can be challenged, the full rebuttal letter - every argument, the case law, FOS precedents, ready to send - costs £49.99. No hidden fees, no subscriptions!
  • Money-back guarantee:if the pack isn't useful, tell us within 14 days and we refund you in full. No forms, no hoops.

A small one-off fixed fee - not a lawyer's hourly bill.

Questions

What you might be wondering.

What does market value mean on a written-off car?

Broadly, what it would have cost to buy the same car — same model, age, mileage and condition — immediately before the accident.

It is not what you paid, what you owe on finance, or what a single trade guide prints. It is replacement cost.

My insurer’s valuation is too low. Can I challenge it?

Yes, and these are among the most successfully challenged decisions in motor insurance. The strongest evidence is current advertisements for genuinely comparable vehicles.

Add anything that makes your car better than the average example — service history, low mileage, recent work, specification.

They said the offer is final. Is it?

"Final" is a negotiating word, not a legal one. Insurers expect first offers to be accepted, and most are.

A reasoned written response with comparable advertisements attached frequently produces a better number. If it does not, the Ombudsman is free.

What if I owe more on finance than the payout?

The insurer pays market value regardless of your finance balance — the shortfall is a separate problem, and it is what GAP insurance exists to cover.

It is not a reason the valuation itself is wrong, but it is a strong reason to make sure the valuation is right.

Is this legal advice?

No. smarterclaims publishes legal information and writes letters you can send yourself — like a digital version of a published legal guide. We are not a law firm and we do not give advice.

If your case needs professional representation, we will tell you, and we can introduce you to the right people if you ask us to.

What does it cost, and do I pay before I see anything?

Checking whether you have a case is free. You see the analysis and the arguments before you pay anything.

The rebuttal letter is £49.99. It comes with an explanation of where you stand and a step-by-step plan.

There is a no-questions-asked money-back guarantee. If the pack is not useful, tell us within 14 days and we refund you in full.

Will complaining make my insurer harder to deal with?

It should not, and firms are required to handle complaints fairly. Insurers deal with complaints as routine business — a well-argued letter tends to be taken more seriously than an angry phone call, not less.

Free tool | Before anything goes wrong

Still haven't filed a claim?

Completely free. Get ahead of a refusal before it ever happens — check your cover for the gaps insurers rely on, so you can avoid the pitfalls and traps. No charge, no account.

Free

Policy check

See where your cover falls short — before you ever need to use it.

  • A plain-language gap report on your policy.
  • Spot the excuses before they cause a problem.
  • Only buy the cover you need.
Check my policy
Steve Smart — the insurance expert behind smarterclaimsMeet Steve

Who's behind this

The playbook this runs on.

Forty years inside the insurance industry, in both senior legal and commercial roles. Former UK General Counsel at AIG. Current Chairman of Lancashire Insurance UK. Regular voice on LBC radio. Steve has watched the same disputes come up again and again — and built the library of arguments that smarterclaims runs on, based on his decades of experience.

Former
UK General Counsel, AIG
Chairman
Lancashire Insurance UK
Background
Solicitor & Lloyd’s broker
As heard on
LBC radio
“I've spent forty years on the inside of insurance. The same excuses come up again and again, and most consumers don't know how to overcome them. This is the tool I wish my clients had before they called me.”Steve Smart
More about Steve

Real people, real results

People we've helped.

5 clients · scroll

Real clients we have helped, shared with their written permission.

As heard onLBC radio
No-questions-asked money-back guarantee.If your pack isn't useful, we refund you in full. You risk nothing.

Claim smarter.

Describe what happened. We'll match it to the argument, and you'll have the rebuttal in minutes.

  • Free to check
  • No account
  • Takes 60 seconds