They said you failed to disclose.

Insurance non-disclosure?

The law they quote changed in 2013.

As a consumer you do not have a duty to volunteer everything you can think of. You have a duty to take reasonable care not to answer their questions wrongly. That is a different thing — and a lot of refusal letters have not caught up.

  • Free to check
  • No account
  • Takes 60 seconds
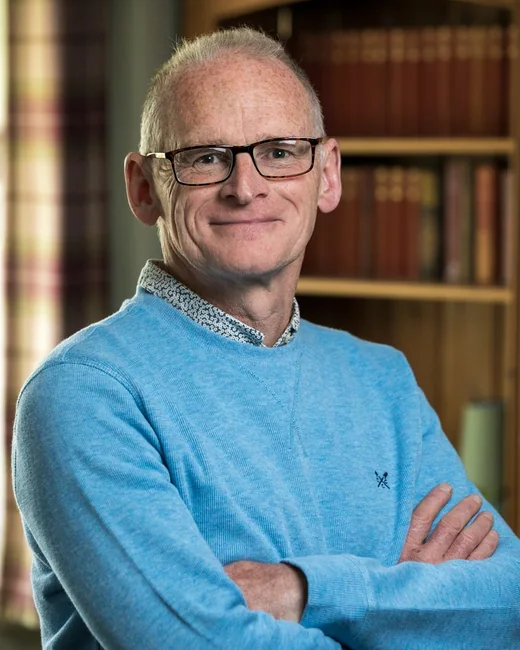
Steve SmartWho's behind thisSteve Smart · Former UK General Counsel, AIGHelped people recover £25M+ from rejected claims

Re: Your claim

Dear ,

We have now completed our review of your claim.

You failed to disclose a material fact. We have therefore avoided your policy from inception and returned your premium.Had we been aware of this information, we would not have offered cover on the terms provided.Your duty of utmost good faith required you to disclose all material facts.The policy is void ab initio and no claim will be paid.

We therefore regret that we are unable to meet your claim on this occasion.

Yours sincerely,

Claims Department

The wording varies between insurers. The argument does not. Typical wording — not a quote from any named insurer.

What they mean

Non-disclosure, translated.

Avoidance is the most serious thing an insurer can do. It does not just refuse this claim — it treats the policy as though it never existed, returns your premium, and leaves you having to declare a voided policy every time you buy insurance again for years.

The stated reason is usually that something was not told to them: a previous claim, a medical condition, a modification, a conviction, who really drives the car.

Where it overreaches

And here is the problem.

Here is the thing worth knowing. The old law asked consumers to volunteer every "material fact" and to observe a "duty of utmost good faith". For consumer insurance, that was swept away in 2013. What replaced it is narrower and much fairer: a duty to take reasonable care not to make a misrepresentation in answer to the questions you are actually asked.

Yet refusal letters still arrive quoting "material facts" and "utmost good faith" — language that has not applied to consumer policies for over a decade. When a letter is arguing under the wrong law, that is not a technicality. It usually means the questions the law does ask have not been worked through at all.

And those questions are demanding. Was there a clear question? Did you fail to take reasonable care? Was it careless or deliberate? Would the insurer genuinely have done anything differently? Each one has to be answered before avoidance is available — and the burden of most of them sits with the insurer.

The counter-arguments

How it gets answered.

These are the points that put the burden back where it belongs. Not every one will apply to your case — the letter we write picks the ones that do.

01

The duty is to answer their questions carefully — not to guess what matters.

Under the 2012 Act, a consumer’s duty is to take reasonable care not to make a misrepresentation when answering the insurer’s questions. There is no general duty to volunteer information nobody asked you about.

So the first question is direct: what exactly were you asked, and how? If they never asked, it is very hard to say you misrepresented — and a letter built on "you should have told us" rather than "you answered this question wrongly" is arguing under law that was repealed for consumers.

CIDRA 2012, s.2
02

Careless or deliberate? That is the whole case.

The remedy turns entirely on this. If the misrepresentation was deliberate or reckless, the insurer can avoid the policy and keep your premium. If it was careless — an honest mistake, a misunderstood question, a forgotten detail — the remedy is proportionate to what would have happened had they known: if they would have declined cover, they can avoid but must return your premium; if they would have charged more, the claim is reduced proportionately; if they would have imposed different terms, those terms apply.

Crucially, careless is the default. A misrepresentation is presumed careless unless the insurer proves it was deliberate or reckless. So a letter that jumps straight to avoidance while describing what sounds like an honest mistake has helped itself to the harshest remedy on the list without establishing the right to it.

CIDRA 2012, s.5 & Sch 1
03

Would it actually have changed anything?

Not every inaccuracy counts. It only qualifies if the insurer can show that, but for the misrepresentation, it would not have entered into the contract at all or would have done so on different terms.

That is a specific, evidenced assertion about their own underwriting — not a rhetorical line. Ask them to demonstrate it. Underwriting criteria differ enormously between insurers, and "we would not have covered you" is a claim that has to be backed up.

CIDRA 2012, s.4
04

Was the question clear, and was it even about this?

Reasonable care is judged against the question you were actually asked, including how clearly it was put. Vague, compound, or ambiguous questions do not support strong remedies, and the standard takes account of the type of policy and how it was sold.

Ask for the question as presented at the point of sale — the screen, the script, the form. What was asked is often noticeably less precise than what the refusal letter now says was asked.

CIDRA 2012, s.3
05

Avoidance has to be proportionate to what you did.

Insurers must handle claims fairly and must not unreasonably reject them, including by avoiding a policy. Avoidance in response to an honest, immaterial mistake invites exactly that challenge.

It is also worth spelling out the consequences to them in writing. A voided policy follows you around for years, and the disproportion between an honest slip and that outcome is itself part of the argument.

FCA ICOBS 8.1.1R

Sources: Consumer Insurance (Disclosure and Representations) Act 2012 · FCA Handbook — ICOBS 8.1 (claims handling)

How it works

Four steps.

You do not have to make these arguments yourself. That is what we are for.

Start free now • No documents neededStart free now

Tell us about your problem

Describe in plain English what happened and your current concern. Takes 60 seconds. We'll give you clear guidance on whether we can help and what to do next - completely free. You can start right now, even if you don't have your refusal letter with you.

Upload your documents

Drop your refusal letter and insurance policy. Takes 2 minutes. No account needed.

We analyze & draft

Our system identifies the legal flaws in the refusal and writes a professional rebuttal with citations.

Send & get paid

Send the letter to your insurer. Most reverse their decision. If not, escalate to the Ombudsman.

Start free. Pay only if we can help you win.

  • Step 1 - Free:describe your situation in plain English. Takes 60 seconds. We'll tell you honestly whether we can help and explain next steps.
  • Step 2 - Still free:if we think your case is suitable, upload your refusal letter and policy. We'll do a preliminary review at no charge.
  • Step 3 - Pay only if suitable: once we confirm your refusal can be challenged, the full rebuttal letter - every argument, the case law, FOS precedents, ready to send - costs £49.99. No hidden fees, no subscriptions!
  • Money-back guarantee:if the pack isn't useful, tell us within 14 days and we refund you in full. No forms, no hoops.

A small one-off fixed fee - not a lawyer's hourly bill.

Questions

What you might be wondering.

What is non-disclosure in insurance?

It is the allegation that you failed to tell your insurer something they needed to know — a past claim, a medical condition, a modification, a conviction.

For consumer policies the legal framing changed in 2013. The duty now is to take reasonable care not to make a misrepresentation when answering the questions the insurer asks, rather than to volunteer every material fact.

Can my insurer void my policy for something I forgot to mention?

Not automatically. They generally have to show you were asked a clear question, that you failed to take reasonable care in answering it, and that they would have acted differently had they known.

And an honest mistake is treated as careless, not deliberate — which usually means a proportionate remedy rather than avoidance. Careless is presumed unless the insurer proves otherwise.

My insurer quoted my "duty of utmost good faith". Is that right?

For a consumer policy, that language is out of date. The duty of utmost good faith and the duty to disclose material facts were replaced for consumers by the Consumer Insurance (Disclosure and Representations) Act 2012, which came into force in 2013.

A letter still arguing on that basis is often a sign that the questions the current law does ask have not been addressed at all.

What is the difference between careless and deliberate misrepresentation?

It decides what the insurer is allowed to do. Deliberate or reckless means they can avoid the policy and keep your premium. Careless means the remedy has to match what they would have done had they known — return the premium, reduce the claim proportionately, or apply the terms they would have set.

The law presumes carelessness. It is for the insurer to prove deliberate or reckless if that is what they are alleging.

What does "void ab initio" mean?

It means treating the policy as if it never existed, rather than simply cancelling it going forward. Your premium is usually returned and no claim is paid.

It is the most serious step available to an insurer, and it has consequences well beyond the claim — you will normally have to declare a voided policy when buying insurance for years afterwards.

Is this legal advice?

No. smarterclaims publishes legal information and writes letters you can send yourself — like a digital version of a published legal guide. We are not a law firm and we do not give advice.

If your case needs professional representation, we will tell you, and we can introduce you to the right people if you ask us to.

What does it cost, and do I pay before I see anything?

Checking whether you have a case is free. You see the analysis and the arguments before you pay anything.

The rebuttal letter is £49.99. It comes with an explanation of where you stand and a step-by-step plan.

There is a no-questions-asked money-back guarantee. If the pack is not useful, tell us within 14 days and we refund you in full.

Will complaining make my insurer harder to deal with?

It should not, and firms are required to handle complaints fairly. Insurers deal with complaints as routine business — a well-argued letter tends to be taken more seriously than an angry phone call, not less.

Free tool | Before anything goes wrong

Still haven't filed a claim?

Completely free. Get ahead of a refusal before it ever happens — check your cover for the gaps insurers rely on, so you can avoid the pitfalls and traps. No charge, no account.

Free

Policy check

See where your cover falls short — before you ever need to use it.

  • A plain-language gap report on your policy.
  • Spot the excuses before they cause a problem.
  • Only buy the cover you need.
Check my policy
Steve Smart — the insurance expert behind smarterclaimsMeet Steve

Who's behind this

The playbook this runs on.

Forty years inside the insurance industry, in both senior legal and commercial roles. Former UK General Counsel at AIG. Current Chairman of Lancashire Insurance UK. Regular voice on LBC radio. Steve has watched the same disputes come up again and again — and built the library of arguments that smarterclaims runs on, based on his decades of experience.

Former
UK General Counsel, AIG
Chairman
Lancashire Insurance UK
Background
Solicitor & Lloyd’s broker
As heard on
LBC radio
“I've spent forty years on the inside of insurance. The same excuses come up again and again, and most consumers don't know how to overcome them. This is the tool I wish my clients had before they called me.”Steve Smart
More about Steve

Real people, real results

People we've helped.

5 clients · scroll

Real clients we have helped, shared with their written permission.

As heard onLBC radio
No-questions-asked money-back guarantee.If your pack isn't useful, we refund you in full. You risk nothing.

Claim smarter.

Describe what happened. We'll match it to the argument, and you'll have the rebuttal in minutes.

  • Free to check
  • No account
  • Takes 60 seconds