They blamed your medical history.

Travel insurance pre-existing condition claim?

You can’t declare what nobody asked about.

Screening questions are short, vague and answered in a hurry — whether it is a holiday booking, a health policy or a new pet. The refusal that follows is none of those things. Here is what has to be true before a pre-existing condition defeats your claim.

  • Free to check
  • No account
  • Takes 60 seconds
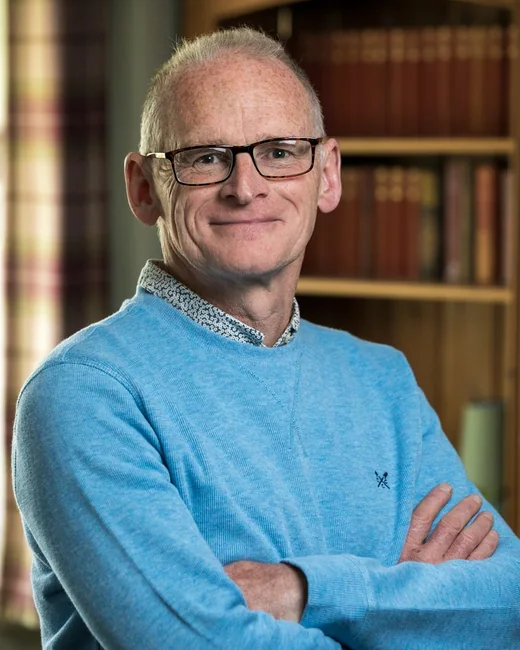
Steve SmartWho's behind thisSteve Smart · Former UK General Counsel, AIGHelped people recover £25M+ from rejected claims

Re: Your claim

Dear ,

We have now completed our review of your claim.

Your claim relates to a pre-existing medical condition which was not declared when the policy was purchased.Had we been aware of your medical history, cover for this condition would have been excluded.The condition you have claimed for is linked to a condition which existed before the policy started.You did not complete a medical screening for this condition.

We therefore regret that we are unable to meet your claim on this occasion.

Yours sincerely,

Claims Department

The wording varies between insurers. The argument does not. Typical wording — not a quote from any named insurer.

What they mean

Pre-existing condition, translated.

Travel policies price on health. Insurers either ask you to declare existing conditions and then rate, exclude or accept them, or they apply a blanket exclusion for anything connected to a condition you already had.

When something goes wrong abroad and the claim is large, the medical file gets read carefully. If anything in it predates the policy, that is where the refusal starts.

Where it overreaches

And here is the problem.

The word doing all the work is "linked". A refusal will connect the thing that happened to you to something in your history, and treat the connection as settled. Often it is nothing of the kind — a previous back problem is not a reason to refuse a chest infection, and insurers reach for the link far more readily than the medical evidence supports.

Then there is what you were actually asked. Screening is usually a handful of broad questions at the end of a booking journey, and the law for consumers asks whether you took reasonable care answering the questions put to you — not whether you volunteered a full history nobody requested.

And you cannot misrepresent something you did not know. Conditions that were undiagnosed, or that you had no reason to consider relevant, are not things you failed to declare.

The counter-arguments

How it gets answered.

These are the points that put the burden back where it belongs. Not every one will apply to your case — the letter we write picks the ones that do.

01

Make them prove the link.

The refusal rests on a medical connection between your claim and your history. That is a clinical question, and it needs clinical evidence — not an assumption drawn from a date order.

Ask them to set out precisely how the condition claimed for is connected to the condition they say you should have declared. Your own consultant’s view carries real weight here, and it frequently contradicts the insurer’s reading of the file.

02

What were you actually asked?

Your duty is to take reasonable care not to misrepresent when answering the insurer’s questions. If the screening never asked about this, or asked in terms so broad that a reasonable person would not have thought it caught your situation, their position weakens sharply.

Ask for the questions exactly as they appeared at the point of sale. What was actually on screen is often much vaguer than the refusal letter now implies.

CIDRA 2012, s.2
03

You cannot declare what you did not know.

Undiagnosed is not undeclared. If you had no diagnosis, no symptoms, or no reason to connect something to your health at the time you bought the policy, there was nothing to misrepresent.

This matters most where a condition is discovered during or after the trip and the insurer then reads it backwards into your history.

04

Careless or deliberate — and would it have mattered?

Even where something was genuinely missed, an honest mistake is careless, not deliberate, and carelessness is presumed unless the insurer proves otherwise. The remedy then has to match what they would have done had they known: excluded that condition, charged more, or declined — not automatically refuse everything.

They also have to show it would actually have changed their decision. Not every omission would have.

CIDRA 2012, ss.4–5 & Sch 1

Sources: Consumer Insurance (Disclosure and Representations) Act 2012

How it works

Four steps.

You do not have to make these arguments yourself. That is what we are for.

Start free now • No documents neededStart free now

Tell us about your problem

Describe in plain English what happened and your current concern. Takes 60 seconds. We'll give you clear guidance on whether we can help and what to do next - completely free. You can start right now, even if you don't have your refusal letter with you.

Upload your documents

Drop your refusal letter and insurance policy. Takes 2 minutes. No account needed.

We analyze & draft

Our system identifies the legal flaws in the refusal and writes a professional rebuttal with citations.

Send & get paid

Send the letter to your insurer. Most reverse their decision. If not, escalate to the Ombudsman.

Start free. Pay only if we can help you win.

  • Step 1 - Free:describe your situation in plain English. Takes 60 seconds. We'll tell you honestly whether we can help and explain next steps.
  • Step 2 - Still free:if we think your case is suitable, upload your refusal letter and policy. We'll do a preliminary review at no charge.
  • Step 3 - Pay only if suitable: once we confirm your refusal can be challenged, the full rebuttal letter - every argument, the case law, FOS precedents, ready to send - costs £49.99. No hidden fees, no subscriptions!
  • Money-back guarantee:if the pack isn't useful, tell us within 14 days and we refund you in full. No forms, no hoops.

A small one-off fixed fee - not a lawyer's hourly bill.

Questions

What you might be wondering.

Can travel insurance refuse a claim over a pre-existing condition?

Only if the position stands up. They generally need to show you were asked a clear question, that you did not take reasonable care answering it, that they would have acted differently, and that the condition is genuinely connected to what you claimed for.

Each of those is arguable, and the medical link is the one that most often fails.

I forgot to declare a condition. Is my claim finished?

Not necessarily. An honest oversight is treated as careless rather than deliberate, and the remedy has to be proportionate to what the insurer would have done had they known.

If they would simply have excluded that condition, that is very different from refusing an unrelated claim outright.

My condition was undiagnosed when I bought the policy. Where do I stand?

Strongly, generally. You cannot fail to declare something you did not know about. If there was no diagnosis and no symptoms you had reason to connect to your health, there was nothing to disclose.

The insurer says my claim is "linked" to an old condition. Can I challenge that?

Yes, and it is often the weakest part of the refusal. A link is a medical question requiring medical evidence, not an inference from chronology.

Ask them to explain the connection, and put your treating clinician’s view alongside it.

Is this legal advice?

No. smarterclaims publishes legal information and writes letters you can send yourself — like a digital version of a published legal guide. We are not a law firm and we do not give advice.

If your case needs professional representation, we will tell you, and we can introduce you to the right people if you ask us to.

What does it cost, and do I pay before I see anything?

Checking whether you have a case is free. You see the analysis and the arguments before you pay anything.

The rebuttal letter is £49.99. It comes with an explanation of where you stand and a step-by-step plan.

There is a no-questions-asked money-back guarantee. If the pack is not useful, tell us within 14 days and we refund you in full.

Will complaining make my insurer harder to deal with?

It should not, and firms are required to handle complaints fairly. Insurers deal with complaints as routine business — a well-argued letter tends to be taken more seriously than an angry phone call, not less.

Free tool | Before anything goes wrong

Still haven't filed a claim?

Completely free. Get ahead of a refusal before it ever happens — check your cover for the gaps insurers rely on, so you can avoid the pitfalls and traps. No charge, no account.

Free

Policy check

See where your cover falls short — before you ever need to use it.

  • A plain-language gap report on your policy.
  • Spot the excuses before they cause a problem.
  • Only buy the cover you need.
Check my policy
Steve Smart — the insurance expert behind smarterclaimsMeet Steve

Who's behind this

The playbook this runs on.

Forty years inside the insurance industry, in both senior legal and commercial roles. Former UK General Counsel at AIG. Current Chairman of Lancashire Insurance UK. Regular voice on LBC radio. Steve has watched the same disputes come up again and again — and built the library of arguments that smarterclaims runs on, based on his decades of experience.

Former
UK General Counsel, AIG
Chairman
Lancashire Insurance UK
Background
Solicitor & Lloyd’s broker
As heard on
LBC radio
“I've spent forty years on the inside of insurance. The same excuses come up again and again, and most consumers don't know how to overcome them. This is the tool I wish my clients had before they called me.”Steve Smart
More about Steve

Real people, real results

People we've helped.

5 clients · scroll

Real clients we have helped, shared with their written permission.

As heard onLBC radio
No-questions-asked money-back guarantee.If your pack isn't useful, we refund you in full. You risk nothing.

Claim smarter.

Describe what happened. We'll match it to the argument, and you'll have the rebuttal in minutes.

  • Free to check
  • No account
  • Takes 60 seconds