They said it was not a storm.

Storm damage insurance claim refused?

The weather station isn’t your roof.

Your tiles are in the garden, but a recording device several miles away did not register the number in their definition. That is not how these claims are meant to be decided — and the small print behind them is already with the regulator.

  • Free to check
  • No account
  • Takes 60 seconds
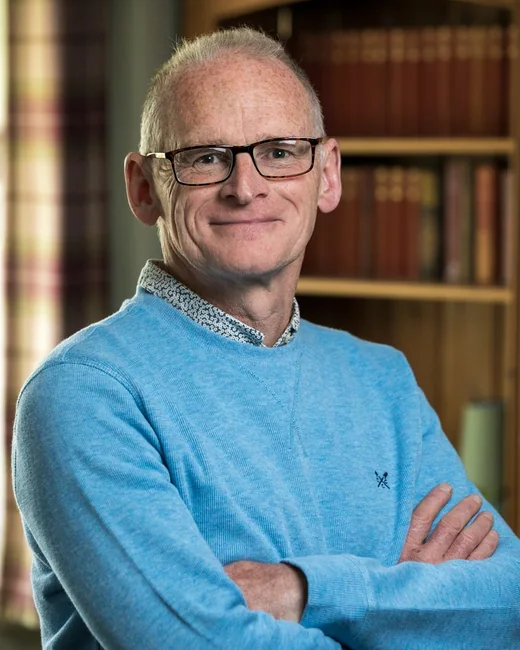
Steve SmartWho's behind thisSteve Smart · Former UK General Counsel, AIGHelped people recover £25M+ from rejected claims

Re: Your claim

Dear ,

We have now completed our review of your claim.

Wind speeds recorded in your area did not reach 55mph and therefore do not meet the policy definition of a storm.Weather data for the date of loss does not support the presence of storm conditions.The damage is attributable to gradual deterioration rather than a one-off storm event.

We therefore regret that we are unable to meet your claim on this occasion.

Yours sincerely,

Claims Department

The wording varies between insurers. The argument does not. Typical wording — not a quote from any named insurer.

What they mean

"It wasn’t a storm", translated.

Home policies cover storm damage, and most define a storm — commonly by a wind-speed threshold, sometimes with rain, hail or snow intensity alongside it. The insurer checks weather data for your postcode on the date, compares it to the number, and if it falls short, the claim falls with it.

There is a reason for having a definition. Without one, every windy night becomes a storm claim.

Where it overreaches

And here is the problem.

The data almost never describes your house. Recorded wind speeds come from the nearest weather station, which can be miles away and nothing like your street for exposure. Gusts are local, and averages hide them. A number that did not appear at the station may very well have appeared at your roofline.

More importantly, the threshold is not the test a fair decision-maker applies. The Ombudsman approaches storm claims in three parts: were there storm conditions, is the damage consistent with storm damage, and was the storm the main cause? Wind speed informs the first question. It does not answer all three, and it is not a trapdoor.

And this is precisely the territory Which? put in front of the FCA in its 2025 super-complaint — home and travel policies whose definitions are unclear when you buy and applied strictly when you claim.

The counter-arguments

How it gets answered.

These are the points that put the burden back where it belongs. Not every one will apply to your case — the letter we write picks the ones that do.

01

The Ombudsman uses three questions, not one number.

Its approach is to ask whether storm conditions were present, whether the damage is consistent with storm damage, and whether the storm was the main cause. A refusal that answers only the first — and answers it with a single figure from a distant instrument — has not engaged with the test.

Framing your complaint around all three puts it on the ground the Ombudsman will actually decide it on.

02

Their data is not from your address.

Ask which weather station the reading came from and how far away it is. Then describe your property: exposure, aspect, position on a hill, the funnelling between buildings, the trees that came down nearby.

Local evidence carries weight — neighbours with damage the same night, photographs, local news, other claims in the street. Gusts are local, and the average recorded miles away is not the wind that hit your roof.

03

A storm is not only wind.

Check the definition you are being held to. Storms include heavy rain, hail and snow, and torrential rain can drive water into a building with no exceptional wind at all.

If they have only tested the wind limb of their own definition, they have not finished the job.

04

Which? has already told the FCA these terms are unfair.

Its 2025 super-complaint covered exactly this: home insurance small print that is unclear and lacks transparency, applied strictly at the point of claim. Storm and flood definitions were central to it.

That does not decide your claim by itself, but it is worth citing — and it is a reminder that if the definition felt invisible when you bought the policy, that is a recognised problem rather than your oversight.

Sources: FCA Handbook — ICOBS 8.1 (claims handling)

How it works

Four steps.

You do not have to make these arguments yourself. That is what we are for.

Start free now • No documents neededStart free now

Tell us about your problem

Describe in plain English what happened and your current concern. Takes 60 seconds. We'll give you clear guidance on whether we can help and what to do next - completely free. You can start right now, even if you don't have your refusal letter with you.

Upload your documents

Drop your refusal letter and insurance policy. Takes 2 minutes. No account needed.

We analyze & draft

Our system identifies the legal flaws in the refusal and writes a professional rebuttal with citations.

Send & get paid

Send the letter to your insurer. Most reverse their decision. If not, escalate to the Ombudsman.

Start free. Pay only if we can help you win.

  • Step 1 - Free:describe your situation in plain English. Takes 60 seconds. We'll tell you honestly whether we can help and explain next steps.
  • Step 2 - Still free:if we think your case is suitable, upload your refusal letter and policy. We'll do a preliminary review at no charge.
  • Step 3 - Pay only if suitable: once we confirm your refusal can be challenged, the full rebuttal letter - every argument, the case law, FOS precedents, ready to send - costs £49.99. No hidden fees, no subscriptions!
  • Money-back guarantee:if the pack isn't useful, tell us within 14 days and we refund you in full. No forms, no hoops.

A small one-off fixed fee - not a lawyer's hourly bill.

Questions

What you might be wondering.

My insurer says wind speeds were too low for a storm. Can they refuse?

Not on that alone, in practice. The Ombudsman applies a three-part test: were storm conditions present, is the damage consistent with a storm, and was the storm the main cause?

A wind-speed threshold from a distant weather station speaks to the first question only, and not very well.

What counts as a storm for home insurance?

Policies usually define it, often by a wind-speed threshold and sometimes with rain, hail or snow intensity as well. Definitions vary between insurers.

The definition is a starting point, not the whole answer — and Which? argued to the FCA in 2025 that these definitions are unfair and lack transparency.

The weather station is miles from my house. Does that matter?

It matters a great deal. Gusts are highly local, and exposure, aspect and surrounding buildings all change what actually hits your roof.

Ask which station was used and how far away it is, then evidence what happened locally — neighbours’ damage, photographs, fallen trees.

They said it was wear and tear, not the storm. What now?

That is a different argument, and it needs different evidence — the question becomes what actually caused the damage.

An insured event that damages something not brand new is still an insured event. Our wear and tear page sets out how that one is answered.

Is this legal advice?

No. smarterclaims publishes legal information and writes letters you can send yourself — like a digital version of a published legal guide. We are not a law firm and we do not give advice.

If your case needs professional representation, we will tell you, and we can introduce you to the right people if you ask us to.

What does it cost, and do I pay before I see anything?

Checking whether you have a case is free. You see the analysis and the arguments before you pay anything.

The rebuttal letter is £49.99. It comes with an explanation of where you stand and a step-by-step plan.

There is a no-questions-asked money-back guarantee. If the pack is not useful, tell us within 14 days and we refund you in full.

Will complaining make my insurer harder to deal with?

It should not, and firms are required to handle complaints fairly. Insurers deal with complaints as routine business — a well-argued letter tends to be taken more seriously than an angry phone call, not less.

Free tool | Before anything goes wrong

Still haven't filed a claim?

Completely free. Get ahead of a refusal before it ever happens — check your cover for the gaps insurers rely on, so you can avoid the pitfalls and traps. No charge, no account.

Free

Policy check

See where your cover falls short — before you ever need to use it.

  • A plain-language gap report on your policy.
  • Spot the excuses before they cause a problem.
  • Only buy the cover you need.
Check my policy
Steve Smart — the insurance expert behind smarterclaimsMeet Steve

Who's behind this

The playbook this runs on.

Forty years inside the insurance industry, in both senior legal and commercial roles. Former UK General Counsel at AIG. Current Chairman of Lancashire Insurance UK. Regular voice on LBC radio. Steve has watched the same disputes come up again and again — and built the library of arguments that smarterclaims runs on, based on his decades of experience.

Former
UK General Counsel, AIG
Chairman
Lancashire Insurance UK
Background
Solicitor & Lloyd’s broker
As heard on
LBC radio
“I've spent forty years on the inside of insurance. The same excuses come up again and again, and most consumers don't know how to overcome them. This is the tool I wish my clients had before they called me.”Steve Smart
More about Steve

Real people, real results

People we've helped.

5 clients · scroll

Real clients we have helped, shared with their written permission.

As heard onLBC radio
No-questions-asked money-back guarantee.If your pack isn't useful, we refund you in full. You risk nothing.

Claim smarter.

Describe what happened. We'll match it to the argument, and you'll have the rebuttal in minutes.

  • Free to check
  • No account
  • Takes 60 seconds